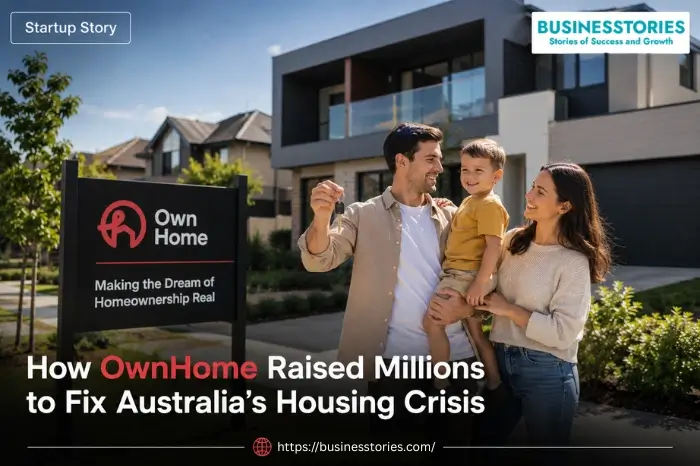
The dream of home ownership in Australia is becoming increasingly elusive. Today, a median-income household needs over 10 years to save for a home deposit. This number keeps growing. For millions of Australians, the dream of home ownership seems more elusive than ever. That is precisely the problem that OwnHome set out to fix.
Two lifelong friends founded OwnHome in 2021. This Sydney-based fintech startup has raised $31 million in funding. The goal is to allow first-time homebuyers to buy without a large deposit. The OwnHome story is not just about smart business. It is about solving one of the most urgent social and economic challenges facing a generation of Australians.
Australia’s Housing Affordability Crisis: The Problem OwnHome Wanted to Solve
To understand why OwnHome exists, you first need to understand just how broken Australia’s housing market has become. The numbers are staggering, and they affect real families every single day.
By the end of 2024, the average Australian home surpassed $1 million in value for the first time. In Sydney, the median house price sits at around $1.4 million. The National Housing Supply and Affordability Council estimates that the median-income household needs 10.6 years to save 20%. That assumes they save diligently while their living expenses keep rising.
The mortgage burden is equally crushing. The Real Estate Institute of Australia found that mortgage repayments now consume 48.1% of median family income. In other words, nearly half of what a family earns goes straight to the bank. For renters hoping to become buyers, the situation is even worse. PropTrack data shows that a median-income renter can afford just 11% of homes sold in any given year.
What makes this crisis deeply unfair is who it locks out.
It is not the irresponsible spender or the poor planner. It’s the nurse, the teacher, and the young professional. Individuals who earn decent salaries but struggle to keep up with rapidly rising property prices. As OwnHome’s co-founder James Bowe put it plainly: “The deck is very much stacked against first-home buyers.”
There is also a structural inequality problem buried inside this crisis. Australians call it the “Bank of Mum and Dad.” Over 60% of first-time buyers rely on their parents’ wealth rather than their own. OwnHome started from one simple, powerful observation: the deposit hurdle has become the real barrier. And if you can remove it, you can change who gets to own a home.
Why Saving for a Deposit Has Become Nearly Impossible
Wage growth in Australia has been painfully slow compared to property price growth. Between 2011 and 2024, median household disposable income grew by 56%. The average home price doubled, rising 104%, during the same period.
Australians worked harder and earned more, but the deposit goalpost moved. For many, the required deposit across most capital cities had reached close to $250,000. Many families cannot save such an amount while paying rent and living expenses.
The Founders Behind OwnHome: A Friendship That Became a Mission
The story of OwnHome begins with two friends from Sydney. James Bowe and Tim Harley, who had known each other since law school. Their bond was so close that Tim reportedly carried the cake at James’s wedding. But beyond their friendship, both men shared a burning desire to solve a problem that had personally affected them and their families.
James spent seven years at Bain & Company in San Francisco. He worked alongside major global venture capital funds, including Tiger Global. He discovered innovative rent-to-own models in San Francisco. Unaffordability must be resolved to facilitate the entry of low-income buyers into the housing market.
He saw firsthand how these models could work. And he began to consider how to bring those ideas back to Australia.
Tim, meanwhile, had built deep expertise in fintech as the head of the Middle East for TransferWise (now Wise). In this role, he led regional strategy and expansion for one of the world’s fastest-growing financial technology companies.
Together, they returned to Australia with a shared mission. As James later explained, “What finally brought us both home was the desire to dedicate ourselves to solving housing affordability. This issue significantly contributed to our initial decision to move overseas.“
From Hotel Quarantine to a Living Company
The OwnHome origin story has a distinctly Australian flavour. While still working their demanding jobs. James is in the UK; Tim is across the Middle East. The pair entered the Commonwealth Bank’s Xccelerate 2020 accelerator program. Juggling jobs and their startup idea, they worked from 10 p.m. to 4 a.m. to meet accelerator deadlines.
Their effort paid off. They won the Xccelerate 2020 program. They received $150,000 in seed funding and valuable mentorship. After returning to Australia, they famously raised their initial seed capital in hotel quarantine during the COVID-19 pandemic. By 2021, OwnHome was officially launched and open for business.
The story of these two friends building a company under those conditions speaks to a deeper truth. Founders who feel a personal, urgent connection to the problem often establish the best startups.
How OwnHome Works: A New Path to Homeownership
OwnHome’s model is elegant and straightforward. It directly targets first-home buyers. Those who earn a solid income and can manage regular monthly payments. These buyers often struggle to save a 20% deposit fast enough for the market.
The Rent-to-Buy Model (Original Offering)
In its original form, OwnHome operated a rent-to-buy model. Here is how it worked:
- A customer selects a home they want to purchase.
- OwnHome buys the home on their behalf.
- The customer moves in and pays a small upfront fee, plus monthly payments.
- Those monthly payments build toward the deposit over time.
- After three to seven years, the customer has the option to buy the home at a pre-agreed price. The annual price is locked in to increase by approximately 3.8%.
This model gave buyers two powerful benefits. First, it removed the need to save a massive deposit upfront. Second, it gave buyers certainty. Locking in the price of a property prevents a rising market from outpacing buyers. For many buyers, the typical home purchase process takes around nine months. OwnHome could cut that down significantly, letting buyers secure their home before prices climb further.
Co-founder Tim Harley summarized the appeal clearly: “By locking in the rate that the property price grows at, customers are protected from a runaway market and can plan their lives with certainty.”
The Deposit Boost Loan (Evolved Product)
As OwnHome grew, the company refined its product to create the Deposit Boost Loan. A more flexible, scalable solution. This product allows customers to purchase a home with as little as a 0% deposit. OwnHome provides the deposit amount as an accelerator loan.
Customers can then secure a standard home loan with any bank or lender they qualify for. Every Deposit Boost Loan customer gets a personal buyer’s agent to help them find the right property at the right price. By May 2024, OwnHome had already approved $5 million in deposit loans, corresponding to $20 million worth of new home purchases. OwnHome plans to support $500 million in purchases over the next 18 months.
OwnHome’s $31 Million Raise: Who Backed Them and Why
In February 2022, OwnHome announced the close of a $31 million Series A funding round. The oversubscribed funding round sent a clear signal of investor confidence in the company’s model and mission.
Square Peg Capital led the round. It is one of Australia’s top venture capital firms and has backed Stripe, Airwallex, and Athena. Square Peg and the Commonwealth Bank of Australia’s X15 Ventures, which had supported James and Tim through the Xccelerate accelerator, made strategic investments.
Other participating investors included Global Founders Capital (GFC), Entrée Capital, AfterWork Ventures, and Possible Ventures. All of these investors had previously backed OwnHome in earlier rounds and chose to double down.
What Made Investors Believe?
Several factors made OwnHome a compelling investment. First, the scale of the problem was undeniable. Over 3,500 applicants had already joined OwnHome’s waitlist at the time of the raise. By August 2024, the company had received more than 15,000 applications. Additionally, the company received over $13 billion worth of loan applications in a single year.
Second, the founding team brought rare credibility. Between them, James and Tim had profound experience across global finance, strategy consulting, and fintech expansion. They were not just building a business. They were solving a problem they knew intimately and personally.
Third, OwnHome’s model addressed a clear and growing market failure. As CBA’s X15 managing director Toby Norton-Smith noted, “This issue is a big problem space, ripe for innovation.” Overcoming the deposit hurdle remains a challenge for many aspiring homebuyers, even those doing well financially, with a higher-than-average income and excellent credit history.
The raise also attracted backing from NAB Ventures (NAB’s venture arm). This further cements OwnHome’s credibility within Australia’s major banking sector.
OwnHome’s Impact: Turning Renters Into Owners
Since its launch, OwnHome has steadily grown its reach and impact. The numbers tell a clear story of a startup gaining real traction in a market desperate for solutions.
By early 2024, OwnHome had received well over 20,000 applications. It had supported 50 families in becoming homeowners. These might sound like small numbers compared to the scale of Australia’s housing crisis. But they represent a meaningful proof of concept and a foundation for significant growth.
After launching the Deposit Boost Loan, the company aimed to support $500 million in home purchases in 12 months. That figure matches what the federal government planned to support through its own $10 billion Housing Fund each year. This is a remarkable comparison for a startup.
A Unique Insight: OwnHome Is Solving Structural Inequality, Not Just Affordability
Most coverage of OwnHome focuses on the affordability angle. OwnHome assists individuals who struggle to save quickly. But there is a deeper story here. OwnHome is directly challenging structural wealth inequality in Australian society.
When 60% of first-home buyers need their parents to help with a deposit, home ownership stops being a reward for hard work. It becomes a reward for being born into the right family. OwnHome breaks that link.
It creates a path for people who are capable, credit-worthy, and financially responsible. But they simply do not have wealthy parents. That is a fundamentally different kind of innovation. It is not just a product. It is a correction to a system that has tilted too far against those without inherited wealth.
What’s Next for OwnHome: The Road Ahead
OwnHome has shown that it can attract capital, build a product, and serve customers at scale. But the company is still in the early stages of its potential. Australia’s housing challenge is enormous, and so is the opportunity to help solve it.
To expand its mortgage broker channel, OwnHome has partnered with major brokers and aggregators like Finsure. This is a smart move. Mortgage brokers are a crucial touchpoint for first-home buyers. Providing brokers with tools such as the Deposit Boost Loan significantly expands OwnHome’s distribution.
Furthermore, the Deposit Boost Loan makes OwnHome’s model particularly effective. It is straightforward enough to scale nationally and potentially internationally. Other countries, including the UK and Canada, face similar housing affordability challenges. The intellectual foundation James Bowe found in San Francisco could extend beyond Australia.
OwnHome will continue to be in demand as long as home prices outpace wages, which is unlikely to change.
Conclusion: Why the OwnHome Story Matters
The OwnHome story is more than a startup funding announcement. It is a reminder that some of the most important innovations do not come from chasing trends. They come after looking at a broken system and refusing to accept it as permanent.
James Bowe and Tim Harley saw a generation of Australians locked out of homeownership due to changing rules, not irresponsibility. They drew on global experience, personal passion, and a solid fintech foundation to build OwnHome into a real solution. And the market responded.
They successfully raised $31 million, with backing from Australia’s biggest banks and leading venture capital firms. This validated the idea that the problem is worth solving and that OwnHome has the right team to address it.
For aspiring homeowners struggling with deposit hurdles, OwnHome offers a genuinely new path. It provides a model worth researching and endorsing for investors and policymakers. Anyone who believes in making the Aussie dream of home ownership accessible to everyone can benefit from this model.
This opportunity extends beyond those fortunate enough to have wealthy parents. OwnHome represents exactly the kind of bold, purposeful innovation that can shift the odds in favor of ordinary Australians.
If you are a first-home buyer exploring your options, visit ownhome.com to learn more about the Deposit Boost Loan and whether it could work for you.
Tabassum Shaik is an Author, Researcher, and SEO Specialist with over 8 years of experience creating informative content on business, startups, entrepreneurship, marketing, technology, and digital trends. She specializes in researching industry trends and transforming complex topics into practical, easy-to-understand insights. Her goal is to help readers stay informed, learn new ideas, and make better business decisions.