Picture this: You launch a business with boundless energy. You have a solid plan. You believe success is inevitable. Then, two years later, the doors close. Sadly, this story repeats itself every single day. In fact, about 20% of small businesses fail within the first year. Roughly half do not make it past five years, according to the U.S. Bureau of Labor Statistics. So, why businesses fail is not just a curious question. It is one every founder must answer before it is too late.
The truth is, most failures follow the same patterns. Entrepreneurs across industries trip over identical pitfalls. The good news? When you know what those pitfalls look like, you can step right around them.
In this article, we cover the 10 most common reasons why businesses fail and provide practical steps to avoid each one. Let us dive in.
1. Lack of Proper Market Research
Imagine building a boat and then realizing there is no water. That is what happens when entrepreneurs skip market research. A groundbreaking CBInsights analysis of over 110 startup post-mortems found that 42% of failed businesses identified “no market need” as the primary reason for shutting down.
You can have the best product on earth. But if nobody wants it, you have nothing. Many founders become overly attached to their ideas. They assume that because they love the product, millions of others will too.
They confuse personal excitement with real demand. This confirmation bias leads them to ignore warning signs, low pre-orders, lukewarm survey results, or blank stares during pitches. Consequently, they pour cash into a product the market simply does not want.
What steps can you take to prevent this mistake?
- First, talk to at least 50 potential customers before writing a single line of code or ordering inventory. Do not sell. Just listen. Ask about their pain points and what solutions they currently use.
- Second, run a smoke test: create a simple landing page, describe your product, and measure sign-ups. If nobody clicks, you have your answer, and you just saved yourself a fortune.
- Third, analyze whether you are entering a growing market or a shrinking one. Even a perfect product cannot survive in a dying industry.
Unique insight: Most founders ask “Would you buy this?” and get polite yeses. Instead, ask, “What would stop you from buying this?” The objections reveal far more than the affirmations ever will. Market research is not about validating your idea. It is about challenging it until only the truth remains.
2. Running Out of Cash Flow
Cash flow is the lifeblood of any business. When it stops, the business dies, fast. A U.S. Bank study found that 82% of small business failures tie directly to poor cash flow management. Profit on paper means nothing if you cannot pay rent on Tuesday. This is a core reason why businesses fail, and it catches even experienced founders off guard.
The issue frequently remains unnoticed. A company lands a huge contract and celebrates. But the client pays in 90 days, while payroll hits every two weeks. That gap, between sending invoices and receiving cash, is where businesses can choke.
Rapid growth, ironically, makes the situation worse. Scaling requires spending on inventory, staff, and marketing long before new revenue arrives. Additionally, many founders mix personal and business finances. It creates a foggy picture of what the company actually has in the bank.
To stay safe, maintain a cash reserve covering at least three to six months of operating expenses. This is your survival buffer. Next, forecast your cash flow monthly. Look six months ahead and identify every potential shortfall before it becomes a crisis.
Furthermore, negotiate better payment terms by paying suppliers later and collecting from customers sooner. Even a 15-day swing can save a company. And if clients consistently pay late, have an honest conversation or consider firing them. One bad customer can ruin everything.
Unique insight: Profitability and cash flow are not the same thing. You can be profitable on paper and still go broke. Always manage cash, not just revenue, as if your business depends on it. Because it does.
3. Weak Business Planning
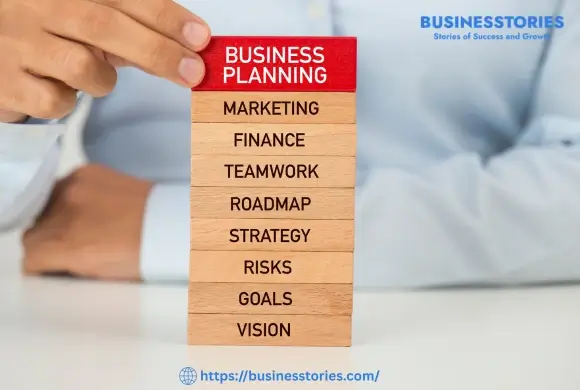
Would you drive across the country without a map? Probably not. Yet many entrepreneurs launch businesses with nothing more than a few notes on a napkin. A weak business plan, or no plan at all, is one of the top reasons businesses fail. A study published in the Strategic Management Journal found that companies with formal written plans are 16% more likely to achieve viability than those without one.
A business plan does more than collect dust on a shelf. It forces you to answer tough questions. Who is your customer? How will you reach them? What makes you different? How much will it all cost? Skipping these questions leads to costly guesswork later. Moreover, without clear milestones, you cannot tell whether you are on track or sliding toward disaster.
Your plan does not need to be 50 pages. But it must cover these essentials:
- A clear value proposition,
- Target customer profile,
- Revenue model,
- Cost structure,
- Marketing approach, and
- 12-month financial projections.
Revisit the plan every quarter. Markets shift. Competitors emerge. A flexible plan is your compass. Rigid plans break, but adaptive ones keep you moving in the right direction.
Unique insight: The real value of a business plan is not the final document. It is the thinking process behind it. The discipline of writing forces clarity. If you cannot explain your business simply on paper, you probably need to understand it better.
4. Ignoring Customer Feedback
Your customers are trying to tell you something. Are you listening? Startups that ignore feedback rarely survive. According to data from PwC, 59% of consumers will abandon a brand after just one or two bad experiences.
That is a brutally short leash. When founders dismiss complaints as “difficult customers” or cling to their original vision despite clear signals, they drift away from the very people who keep the lights on.
The fix is simple but demanding.
- First, build feedback loops into your operations. Send short surveys after purchases. Monitor online reviews. Consider calling customers directly, especially those who may be dissatisfied.
- Second, categorize feedback into two buckets: product issues you can fix quickly and strategic insights that may reshape your direction. Act on the quick wins immediately; they earn trust. Reflect on the strategic ones carefully.
Unique insight: Do not just listen to what customers say. Watch what they do. Behavior reveals the truth. If customers say they love your product but never return, your product has a retention problem, not a satisfaction one. Feedback without action is just noise. Action without feedback is just gambling.
5. Poor Marketing and Branding
“If you build it, they will come” works in movies. Not in business. One of the most painful reasons why businesses fail is simply that nobody knew they existed. A brilliant product, hidden in the dark, stays hidden.
HubSpot research shows that 61% of marketers rank lead generation as their top challenge, and that is among professionals. For new founders, the struggle is even steeper.
Many technical founders assume a fantastic product sells itself. It does not. Others spread themselves too thin across every social platform without a coherent message. The result? A scattered brand that connects with nobody.
Effective marketing starts with a clear answer to one question: Why should anyone care? From there, choose one or two channels where your customers actually spend time and commit to doing those channels exceptionally well.
Unique insight: Marketing is not about shouting louder. It is about being more relevant. A small audience that genuinely trusts you will outperform a large audience that barely notices you, every single time. Invest in relationships, not just reach.
6. Wrong Team or Hiring Mistakes
No founder builds a great company alone. However, hiring the wrong people can dismantle a company more quickly than any competitor could. CBInsights data shows that team-related issues contribute to 23% of startup failures.
Common errors include hiring for skills but ignoring cultural fit, bringing on friends who lack accountability, or delaying tough conversations about underperformance.
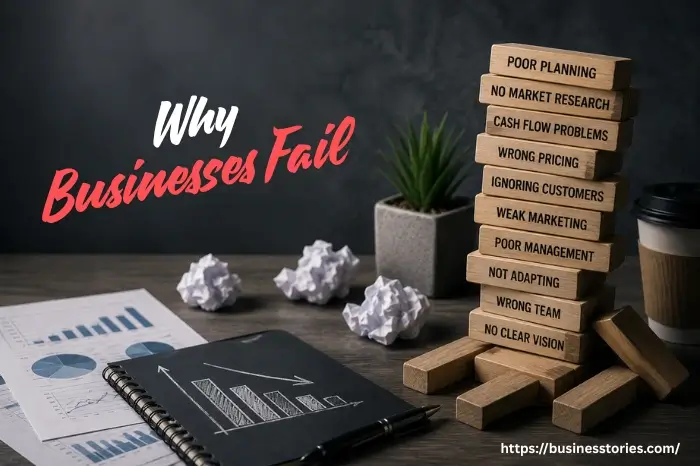
The early team shapes everything: product quality, customer experience, and company culture. Each hire serves as a foundational element. One wrong block weakens the entire structure. Therefore, hire slowly and fire quickly.
Define the values you want your company to embody, and then hire people who already live those values. Skills can be taught; character rarely can.
Unique insight: The most significant hiring mistake is not incompetence. It is indifference. A skilled but disengaged employee does more damage than an unskilled but passionate one, because indifference spreads. Protect your culture fiercely; it is the only competitive advantage you fully control.
7. Pricing Strategy Errors
Price your product too high, and you scare away customers. Price it too low, and you risk quietly going broke. Finding the right price is one of the hardest and most critical decisions an entrepreneur can make.
Many founders, especially first-timers, underprice out of fear. They think low prices attract more customers. In reality, low prices often attract the worst customers: price-sensitive, disloyal, and demanding.
Your price signals value. Set it too low, and customers assume your product is cheap in every sense of the word. Additionally, low prices leave no margin for marketing, research, or mistakes, and mistakes are inevitable.
To price effectively, you must fully understand your costs. Research what competitors charge and, most importantly, test your pricing. Consider raising prices by 10% and observe the results. You may be surprised to find that demand barely moves.
Unique insight: Price is rarely the real objection. When a customer says “it is too expensive,” they usually mean “I do not yet see enough value.” Rather than lowering your price, focus on making your value clearer. The right customers pay for outcomes, not features.
8. Scaling Too Fast (Premature Scaling)
Growth feels intoxicating. New orders flood in. The team expands. The future looks limitless. But scaling before your foundations are solid is like adding floors to a building with a cracked foundation.
Startup Genome Project research identifies premature scaling as the single biggest predictor of startup failure. Companies that scale too early are far more likely to collapse than those that pace themselves.
Premature scaling takes many forms: hiring dozens of employees before processes are documented, expanding to new cities when the first location is still unstable, or pouring money into ads before product-market fit is confirmed.
The result is always the same: rising costs outpace sustainable revenue, quality drops, and the whole operation wobbles. First, confirm that customers are genuinely happy and returning. Then systematize everything. Only after that should you pour fuel on the fire.
Unique insight: Growth is not the goal. Sustainable growth is the goal. A business that grows 200% in one year but then collapses is not a success story. It is a cautionary tale. Build a company that can last, not just one that can launch.
9. Lack of Adaptability and Innovation
Blockbuster had 9,000 stores in 2004. By 2014, they had one. Kodak invented the digital camera and then refused to embrace it. These stories remind us that standing still is the fastest way to fall behind. Markets shift. Technology evolves.
Customer preferences change. Companies that cling to what worked yesterday wake up irrelevant tomorrow.
Adaptability starts with curiosity. Read about adjacent industries. Talk to customers about what is changing in their world. Run small experiments: a new feature, a different channel, a fresh pricing model.
Not every experiment will work. But the habit of experimentation keeps your business alive. Furthermore, create a culture where team members feel safe suggesting changes. The best ideas often come from the frontline, not the boardroom.
Unique insight: Adaptability is not about chasing every trend. It is about staying connected enough to reality that you can tell which trends matter and which are distractions. The goal is evolution, not chaos.
10. Legal and Compliance Ignorance
Legal problems rarely make the list of exciting startup topics. Yet they quietly destroy businesses every year. A single lawsuit, trademark dispute, or regulatory fine can wipe out years of hard work.
Common pitfalls include using the wrong business structure, failing to protect intellectual property, misclassifying employees as contractors, and ignoring industry-specific regulations.
The fix does not require a full-time lawyer. But it does require proactive attention. Form the right legal entity from day one, an LLC or corporation, to protect your personal assets. Trademark your business name and logo early.
Use clear, written contracts with every partner, employee, and client. If you operate in a regulated industry like finance, healthcare, or food, know the rules before you break them. An hour of legal counsel now can prevent a decade of regret later.
Unique insight: Legal problems are like termites. You do not see them until the structure is already damaged. The most expensive legal mistake is not the lawsuit you fight. It is the one you never saw coming. Invest in prevention, not just defense.
Conclusion: Why Businesses Fail — And How You Can Succeed
We have explored a wide range of topics. From skipping market research to scaling too fast, the reasons why businesses fail are rarely mysterious. They are predictable. And predictability is a gift. It means you can prepare.
Building a lasting business demands more than a fantastic idea. It requires relentless curiosity about your customers, discipline with your cash flow, the courage to adapt, and the humility to keep learning. The 10 mistakes outlined above are not traps set by a hostile market. They are choices, and you get to make different ones.
So, what now? Choose one mistake from this list that resonates with you the most. Spend 30 minutes today taking one concrete action to address it. Then move to the next. Small, consistent improvements compound into something remarkable. A business that does not just survive but thrives. Now go build something that lasts.
Frequently Asked Questions About Why Businesses Fail
Q: What are the top reasons why businesses fail?
A: The top reasons include lack of market need. Cash flow problems. Weak planning. Ignoring customer feedback. Poor marketing. Team issues. Wrong pricing. Premature scaling. Lack of adaptability and legal ignorance.
Q: How many small businesses fail in the first five years?
A: According to the U.S. Bureau of Labor Statistics, approximately 50% of small businesses fail within the first five years. Only about 35% survive past the ten-year mark.
Q: Why do businesses fail due to poor cash flow management?
A: Cash flow gaps and expenses before customer payments suffocate businesses. Payroll and rent delays can sink even profitable companies.
Q: What are the early warning signs of business failure?
A: Early signs include declining sales and rising customer complaints. High employee turnover, frequent cash shortages, and difficulty paying bills or suppliers on schedule.
Q: How can entrepreneurs avoid most business failures?
A: Conduct thorough market research and manage cash flow carefully. Write a clear business plan and listen to customers. Hire the right team, price correctly, and stay adaptable as conditions change.
Tabassum Shaik is an Author, Researcher, and SEO Specialist with over 8 years of experience creating informative content on business, startups, entrepreneurship, marketing, technology, and digital trends. She specializes in researching industry trends and transforming complex topics into practical, easy-to-understand insights. Her goal is to help readers stay informed, learn new ideas, and make better business decisions.